Home Equity Title Services

Your Home Equity File. One Provider From Search Through Closing.

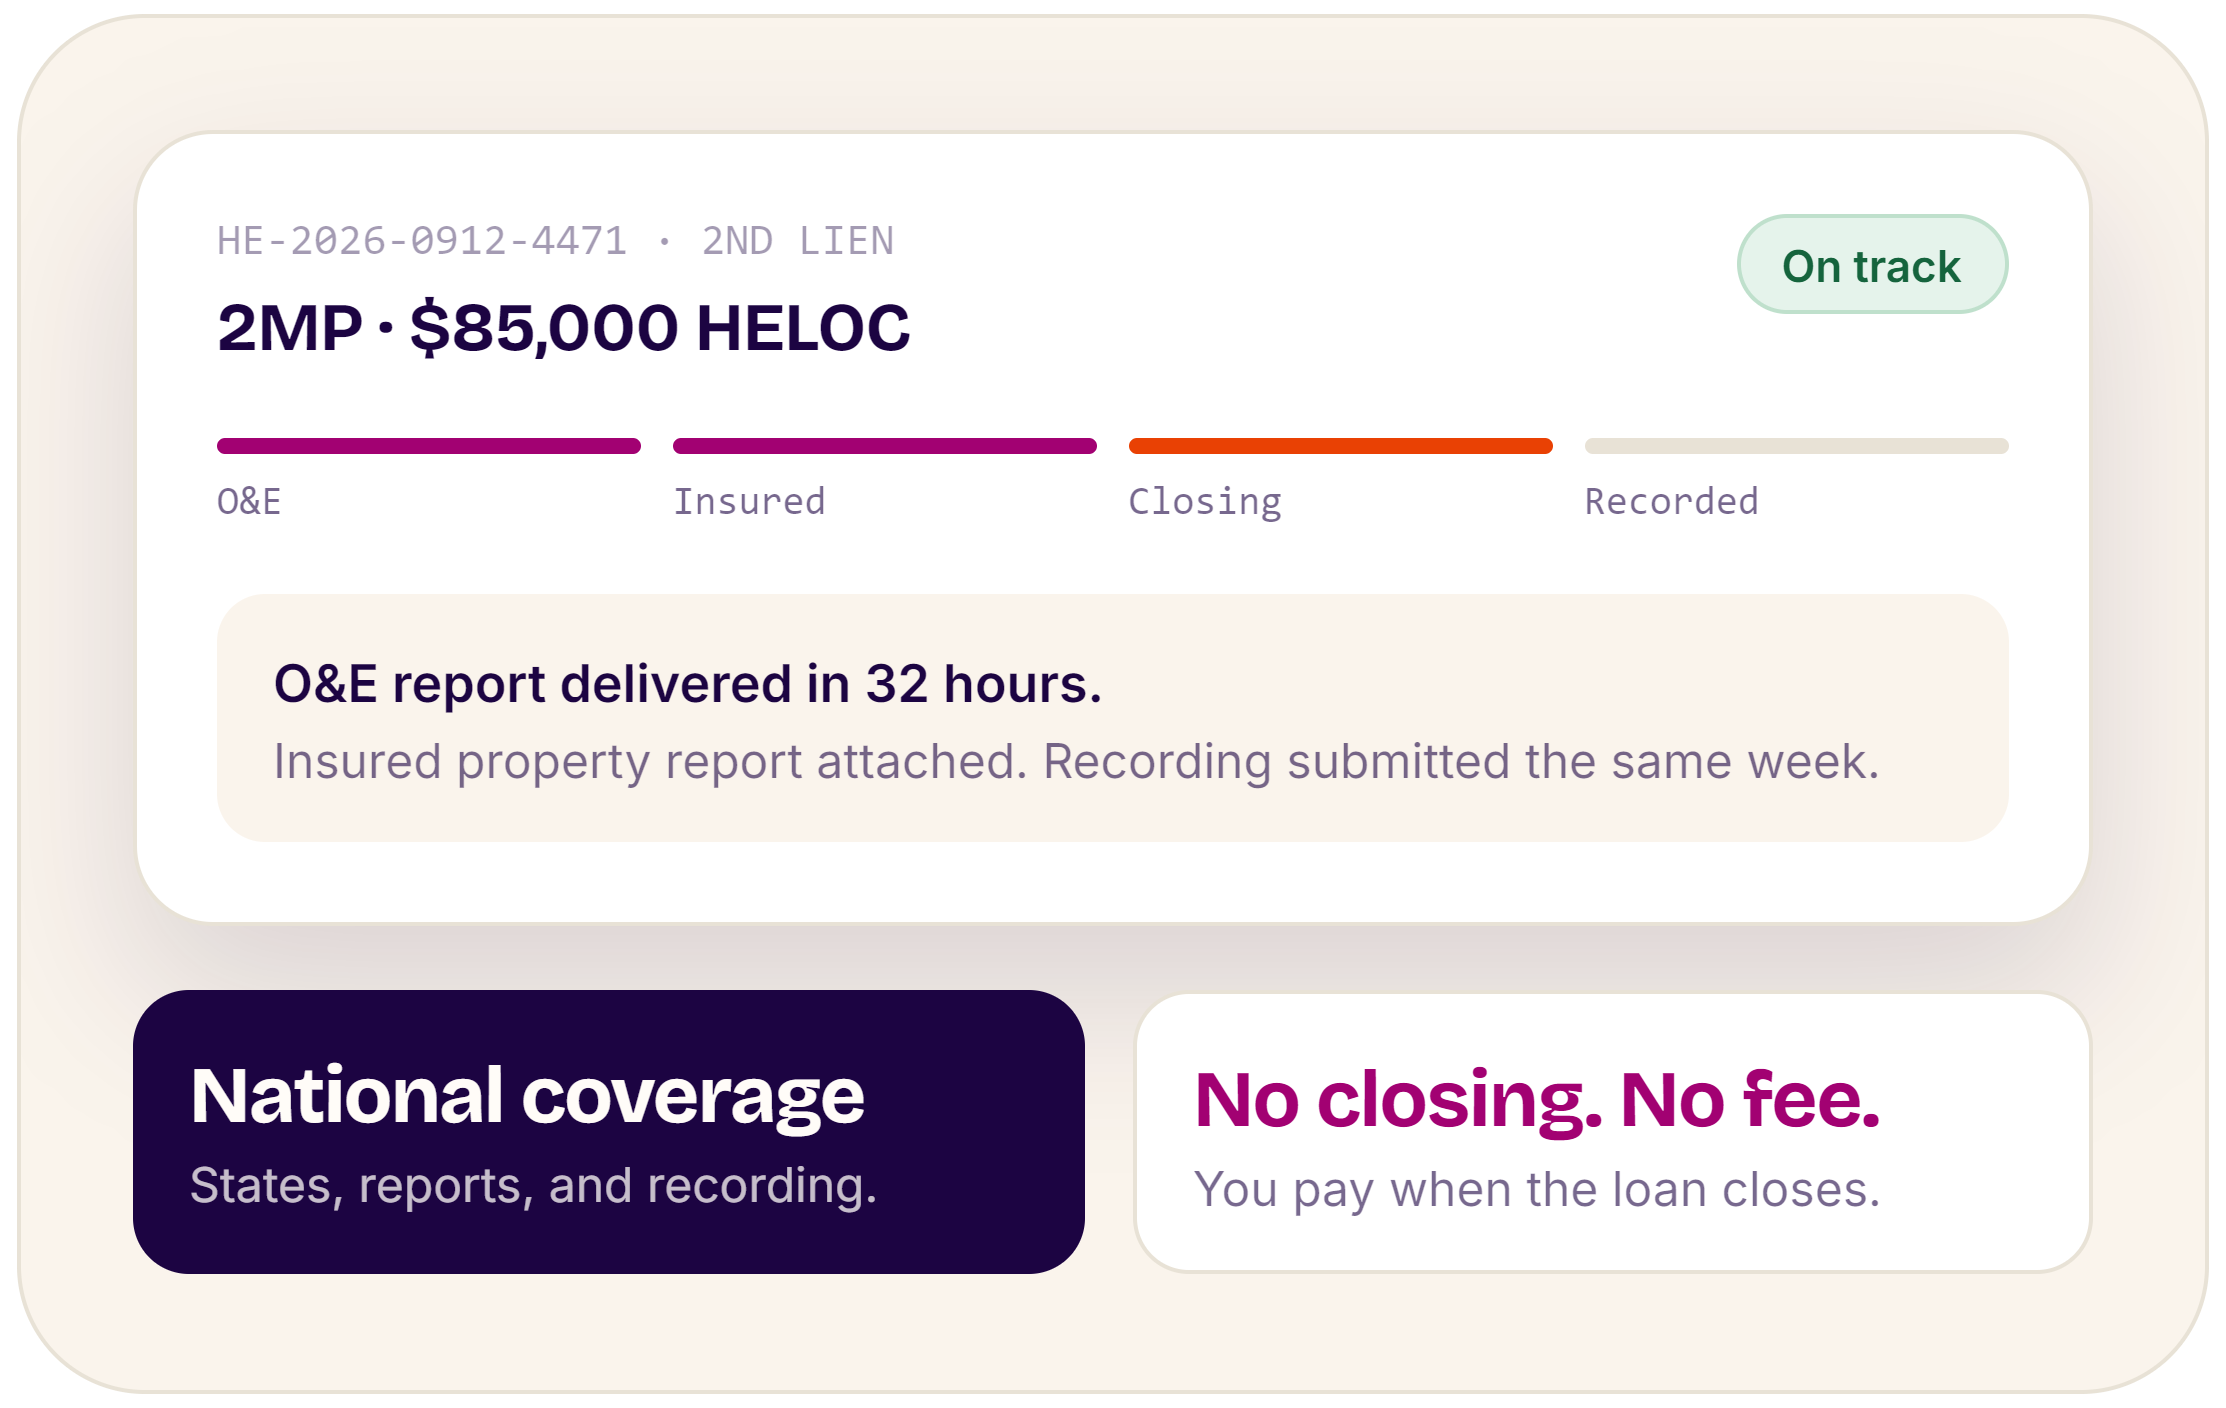
Home equity title services, sized for a second lien. One order. One contact. Title work back in 24–48 hours, with reports, protection, signing, recording, and closing handled.
No portal setup
No Integration
One email address
Home Equity Title Services
Home Equity Turn Time

Built for the speed home equity demands.

Home equity lending has its own pace, risks, and learning curve. The lenders who grow it well have title partners built for that pace.

According to the Mortgage Bankers Association’s 2025 Home Equity Lending Study, “just 50 percent of home equity applications are closing, and turn times are averaging 39 days.” Lending managers describe it in their own words: closings that “rarely came in under 30 days,” and “days and weeks of research to confirm our lien position.”

Behind every one of those applications is a borrower with a roof to replace, a kitchen to finish, a tuition bill due, or card balances to clear. Every extra day is a chance for them to take another offer. And if you’re a credit union that covers closing costs as a member benefit, every file that falls through still carries its title, search, and recording costs.

Building a home equity program means learning what a second lien actually needs: a fast, confident read on lien position, the right level of protection, and a team that treats every file as urgent. Link Title gives home equity lenders dedicated resources and specialized, high-urgency workflows designed around second-lien files, so your team can stay focused on the borrower.

The bottom line: home equity deserves its own playbook. The right title partner brings urgency, dedicated people, and second-lien experience to help you move up the learning curve faster. What a second lien needs from title, and which of the five levels of protection fits, is in the coverage ladder below.

The numbers lending managers live with.

From the MBA’s 2025 study and lending managers’ own words.

  • 50% of home equity applications close (MBA 2025 Home Equity Lending Study)
  • 39-day average turn time, application to close (MBA 2025 Home Equity Lending Study)
  • “Rarely under 30 days”: how one lending manager described closings before switching vendors
  • “Days and weeks” of research to confirm lien position, in another manager’s words

Send us one file

One address. Title work back in 24–48 hours. You pay at closing.

Your borrowers shouldn’t wait weeks for lien position confirmation. Send us one live home equity file. We’ll return the title work within 24 to 48 hours, then manage signing and recording from start to finish. You pay only when the loan closes.

One address

Send the file. No portal setup, no integration work.

24–48 hours

Title work back, lien position confirmed.

No closing. No fee.

Signing and recording handled as one file. You pay at closing.

What we deliver

Every step of the home equity file, under one roof.

No vendor stitching, no handoff gaps. We report, insure, record, and close.

O&E reports

Deep data plant access plus online search, delivered within 48 hours.

Lien protection (2MP)

Our 2nd Mortgage Protect program matches coverage to the second-lien position: cost matched to risk.

Recording solution

Submission within five days and e-recording across 93% of our national footprint.

Closing support

Closing and post-closing support for your borrowers, every step of the way.

Coverage options

Match protection to the risk on the loan.

Loan amount, purpose, LTV, borrower credit, and investor needs drive where a file lands on the ladder, from uninsured reporting to a junior loan policy.

Lower cost

Broader protection

Uninsured

Legal & vesting report

Adds legal description and vesting detail for underwriting.

Uninsured

O&E report

Ownership and encumbrance data for a quick read.

Insured · 2MP · Most used

2nd lien protection program

Insured O&E report or insured property report: our most-used option.

Insured

Attorney opinion letter (AOLPro™)

An insured attorney’s opinion on title, used in place of a loan policy.

Insured

Junior loan policy (JLP)

Full policy coverage for the highest-exposure files.

24-48hr

O&E report delivery

93%

of national footprint e-recorded

5day

recording submission

25+ yrs

title and mortgage operations

What lenders ask before sending the first file

“Will my investor accept an insured report instead of a policy?”

On most second liens, yes. Where your investor requires a policy, you order the junior loan policy on the same file. We match the level to your investor’s rules, and we’ll tell you if a file needs more than you ordered.

“Does this work inside our LOS?”

Yes. We integrate with Encompass, Calyx, and MeridianLink. Not on one of those? Email ordering works from day one, with no setup required.

“What happens when the title is messy?”

You hear about it before closing, in the report, with a recommendation. A complex title gets the level that protects you, plus a curative conversation, not a cheaper report and a surprise later.

“Who do I talk to when I have a question?”

A real person who knows your files. You get a named contact, not a ticket queue.

“What does a test cost me?”

One address. Send us one live file, and we’ll return the title work in 24–48 hours. No closing. No fee.

Pricing

How Does Pricing Work?

Two ways to buy, and you choose per program. With half of home equity applications never closing (MBA, 2025), the difference between the two is roughly half your report spend.

Ask for both models quoted against your last 90 days of home equity volume, closed and fallen through. The right answer depends on your close rate, and the numbers will show it.

Option 1

Per Component

You pay for every report, including the files that never close.

Option 2

Per Closed Loan

You pay only for the ones that do.

FAQ

Questions About Home Equity Title

Have a specific question? Talk to our team

Speed is a priority at Link. With access to instant title solutions, we can typically fulfill more than 75% of our orders the same day they’re received—helping lenders keep home equity loans moving. Orders requiring additional research or review may take longer.

Our focus is simple: speed with quality. Link combines access to instant title solutions with comprehensive title resources and personalized support. When a file has title complications, we identify the issues and recommend next steps to help you address them before closing.

Yes. Link can tailor reports to your lending requirements, including additional information or custom report fields your team needs. Our in-house technology allows us to make these additions quickly, so you receive reports that fit your workflow.

Yes, in practice. Your investor and your own risk policy will require you to know who owns the property and what’s recorded against it before you take a second-lien position, and some state rules say so outright. Ohio’s credit union rule requires that credit unions “obtain a title search of the property securing home equity and second mortgage loans for outstanding liens” (Ohio Administrative Code 1301:9-2-23(C), effective July 8, 2024). A HELOC search is a current-owner search, not the full multi-decade search a purchase needs, so it’s faster and cheaper. Read: What an O&E report is, and when it’s enough.

Not always. Many home equity files run on an insured report rather than a full policy. The highest-exposure files, and any file where the investor requires it, get a junior loan policy. You can’t safely skip the search and the recording. Read: The five levels of protection.

Your mortgage is recorded behind the first mortgage, so the first lender is paid before you if the property sells or forecloses. In most states, position follows recording order, which is why the recording step matters as much as the search: until your mortgage is on record, you don’t hold the position you priced the loan on. Read: Who tracks your mortgage to recording.

Send Us Your Next Home Equity File.

One order covers the report, the protection, the recording, and the closing. One contact handles your file. Most title work is back within 24 to 48 hours, and you pay when the loan closes.